A complete commercial insurance submission includes the ACORD applications for each line, currently valued loss runs with a five-year summary, exposure schedules such as the statement of values and driver list, current policy information and a short account narrative. Commercial insurance submission automation assembles these pieces from one set of data instead of retyping them for every market.
Incomplete submissions are the main reason underwriters push an account to the bottom of the pile. A market that receives a clean, complete package can quote in days. A market that has to email back three times for missing pieces may not quote at all before the renewal date. This checklist covers what to include, line by line, and how to build the package so each market gets the same accurate data.
The core checklist
| Item | Required for | Notes |
|---|---|---|
| ACORD 125 Commercial Insurance Application | Every commercial submission | Applicant details, operations, prior carriers, loss history summary |
| Line sections (ACORD 126, 127, 130, 131, 140 as applicable) | Each line being marketed | GL, auto, workers comp, umbrella and property detail |
| Loss runs, five years plus current | Every line | Currently valued, within 60 to 90 days |
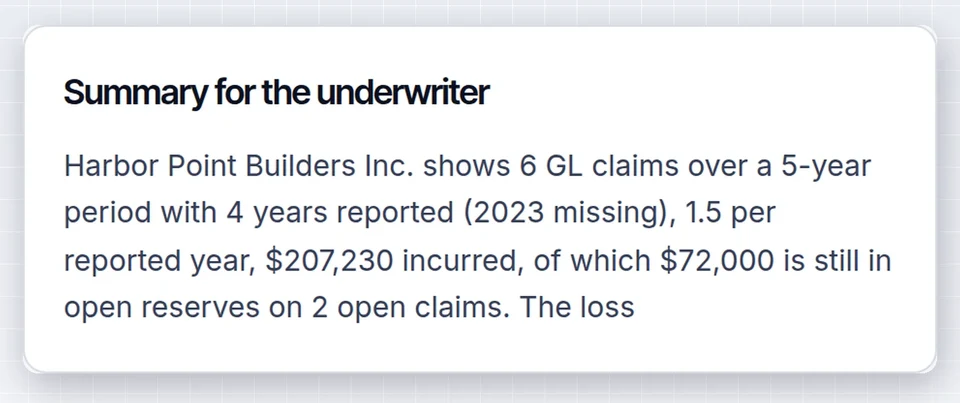
| Loss summary by policy year | Every line | Claim counts, paid, reserve, incurred, earned premium, loss ratio |
| Large loss narratives | Any claim above the market's threshold | What happened, status, what changed afterwards |
| Statement of values (SOV) | Property, inland marine | Per location values and building characteristics |
| Driver list and vehicle schedule | Commercial auto | Driver names, dates of birth, license numbers and years of experience; VINs and stated values |
| Payroll by class code and experience mod worksheet | Workers compensation | Estimated and last audited payroll |
| Current declarations and schedule of underlying | Umbrella and excess | Limits, carriers, premiums |
| Account narrative | Every submission | Operations, management, safety programs, reason for marketing |
| Financials or revenue history | Where requested | Revenue by year, sometimes financial statements |
| Supplemental applications | Specific classes and markets | Contractors, habitational, products, cyber |
Our ACORD forms page covers which ACORD forms apply to which line in more detail.
Loss runs hold the whole submission together
Applications can be prefilled from the agency management system in an afternoon. Loss runs depend on carriers, and carriers work on their own schedule. That makes loss runs the critical path of almost every renewal, and the reason a good renewal workflow starts 120 days before expiration.
What the loss run section needs
- Every term for five years plus the current term, for every line being marketed. See how many years of loss runs for a submission.
- Valuation dates within 90 days of submission, ideally within 60. See currently valued loss runs.
- No-loss letters for any term without claims.
- A summary that ties to the carrier reports. Underwriters will check.
- Loss ratio per year and for the period, calculated on earned premium. The method is in how to calculate loss ratio from loss runs.
For the request itself, follow how to request loss runs from any carrier.
Exposure schedules
Statement of values
The SOV lists every location with address, occupancy, construction class, year built, square footage, number of stories, protection class, sprinkler status, roof age and values for building, contents and business income. Property markets rate from it, so errors flow straight into price. Check that location numbers on the SOV match the ACORD 140 and the property loss runs.
Driver list and vehicle schedule
Commercial auto underwriters want every driver with date of birth, license state and number, years licensed and hire date, and every vehicle with year, make, model, VIN, garaging address and cost new or stated value. Markets usually order motor vehicle records themselves from the driver list, so accuracy matters more than presentation.
Payroll and class codes
Workers comp submissions need payroll by class code by state, the current experience mod worksheet and the last audit. Workers comp claims also deserve their own review before the submission; see workers comp loss runs and the experience mod.
The account narrative
A one to two page narrative is the cheapest way to improve a submission. Underwriters read it first. Cover these points in plain language.
- What the business does, where, and for whom.
- How long it has operated, and the management's experience.
- Material changes since the last renewal (new locations, acquisitions, discontinued products).
- Safety and loss control programs, with specifics.
- An explanation of any large or unusual losses and what changed afterwards.
- Why the account is being marketed and what the insured wants (limits, deductibles, coverage changes).
Quality checks before sending
- Named insured matches across applications, loss runs, SOV and declarations.
- Prior carrier list on the ACORD 125 matches the carriers on the loss runs.
- Loss summary totals tie to the carrier reports.
- Locations and vehicles on schedules match those on the applications.
- Effective dates and requested limits are consistent across every form.
- No internal notes or other clients' data left in any file.
- File names include the insured name and document type.
A renewal timeline that leaves room for markets
The checklist only helps if the pieces arrive in time. This schedule works for most middle market renewals, using days before expiration.
| Days out | Step |
|---|---|
| 120 | Renewal meeting with the insured, letter of authority signed, loss run requests sent to every carrier |
| 110 to 100 | Updated SOV, driver list, payroll and narrative collected from the insured |
| 100 to 95 | Loss runs received and summarized; gaps and stale reports re-requested |
| 90 | Complete package sent to all markets at once |
| 60 to 45 | Quotes received, questions answered, open claims refreshed if needed |
| 30 | Proposal presented to the insured |
Most slippage happens in the first thirty days. If loss runs are still outstanding at day 95, the whole schedule compresses, and markets get less time to work the account.
Sending to multiple markets
When an account goes to several markets, send each one the same complete package at the same time. Staggered or uneven packages lead to quotes on different data, and comparing those quotes later is painful. Keep a log of what went to which market and when, and record each market's questions so the answers can go to all of them.
What commercial insurance submission automation does
Most of the work in a submission is moving the same facts between documents. The named insured, locations, drivers, prior carriers and loss history appear in the applications, the schedules and the loss summary. Automation means entering or importing those facts once and producing every document from them.
LossRunReports handles the loss run side end to end and builds the submission pieces that depend on it. It requests loss runs from each carrier with the signed letter of authority, follows up on day 3, 7 and 14, receives replies on a dedicated inbound address or secure upload links, and reads PDF, scanned, XLSX and CSV reports into one claims schema. It reconciles totals, flags gaps, duplicates and stale valuations, builds the five-year summary with loss ratio, and assembles renewal submission data including ACORD data, the SOV and driver lists. Details are on our commercial insurance submission automation page, and the loss run software page describes the request and reading workflow.
Printable checklist
- ACORD 125 plus each line section
- Loss runs, five years plus current, valued within 90 days
- No-loss letters for clean terms
- Loss summary with loss ratio by year
- Large loss narratives
- SOV for property
- Driver list and vehicle schedule for auto
- Payroll by class and mod worksheet for workers comp
- Schedule of underlying for umbrella
- Account narrative
- Supplementals and financials where required
- Consistency checks completed